The storm passes.
We make you whole.
When your insurer lowballs the claim, Vanguard documents every loss and negotiates for the full settlement your policy owes. No upfront fees.
We fight for you.
Not the insurer.
Vanguard Claims Solutions is a licensed public adjusting firm that represents policyholders, never insurance companies. We maximize your settlement from day one.

Results that speak for themselves.
From a lowball offer to a fair settlement.
Real claims. These are the first offers our clients were handed, and what we recovered after Vanguard stepped in.
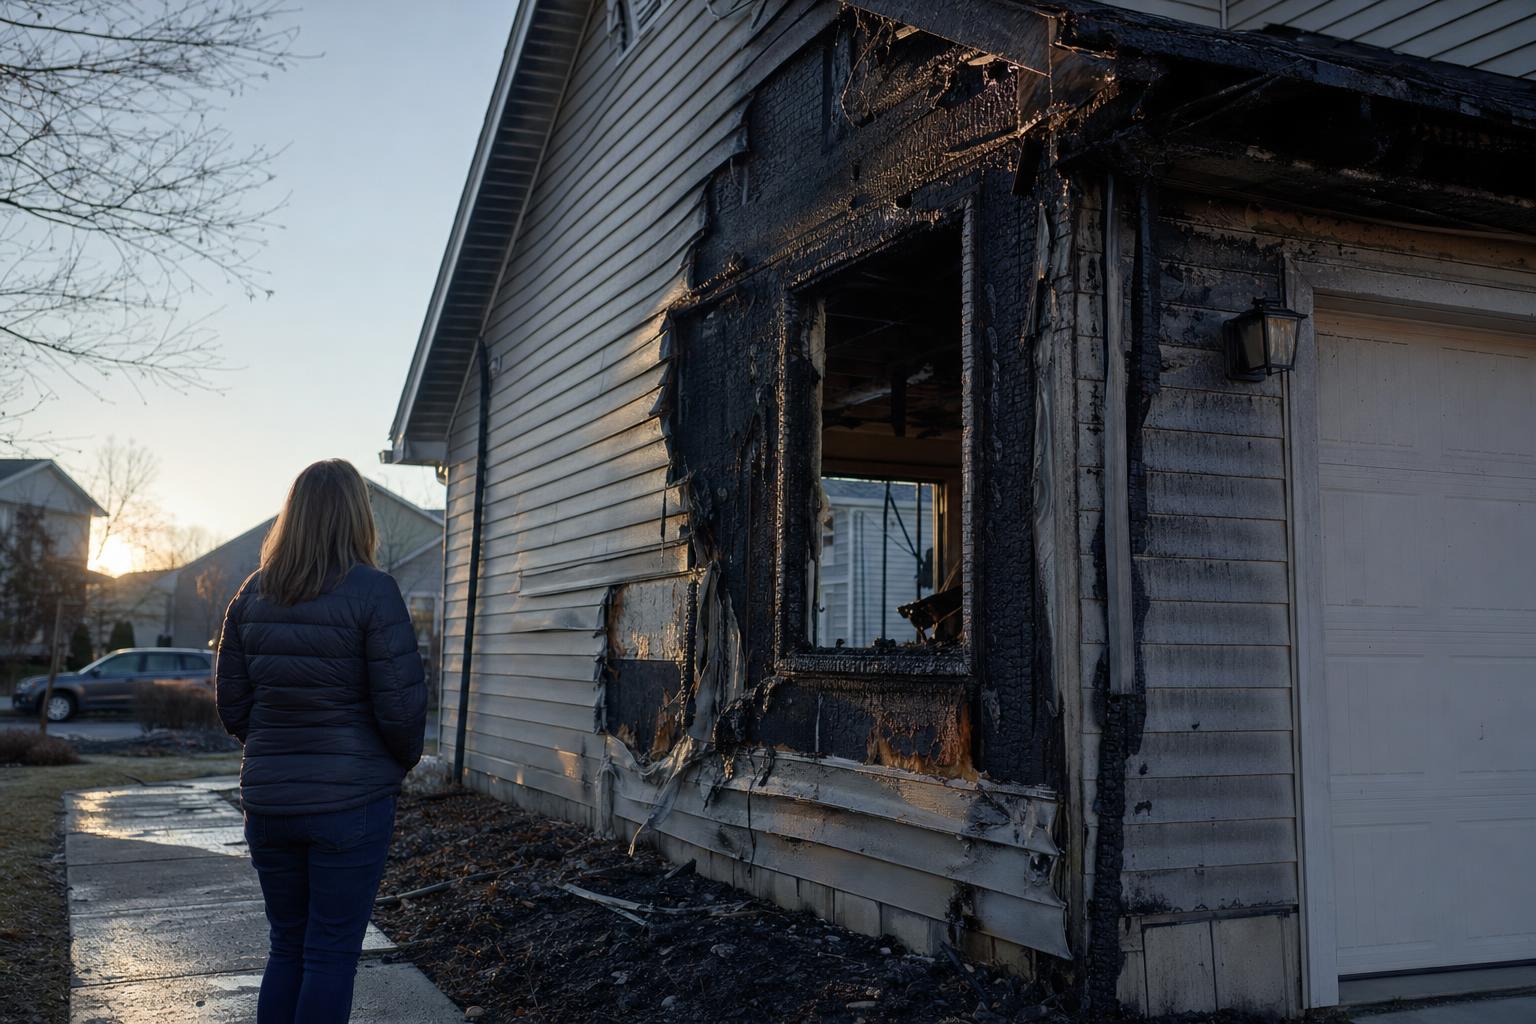
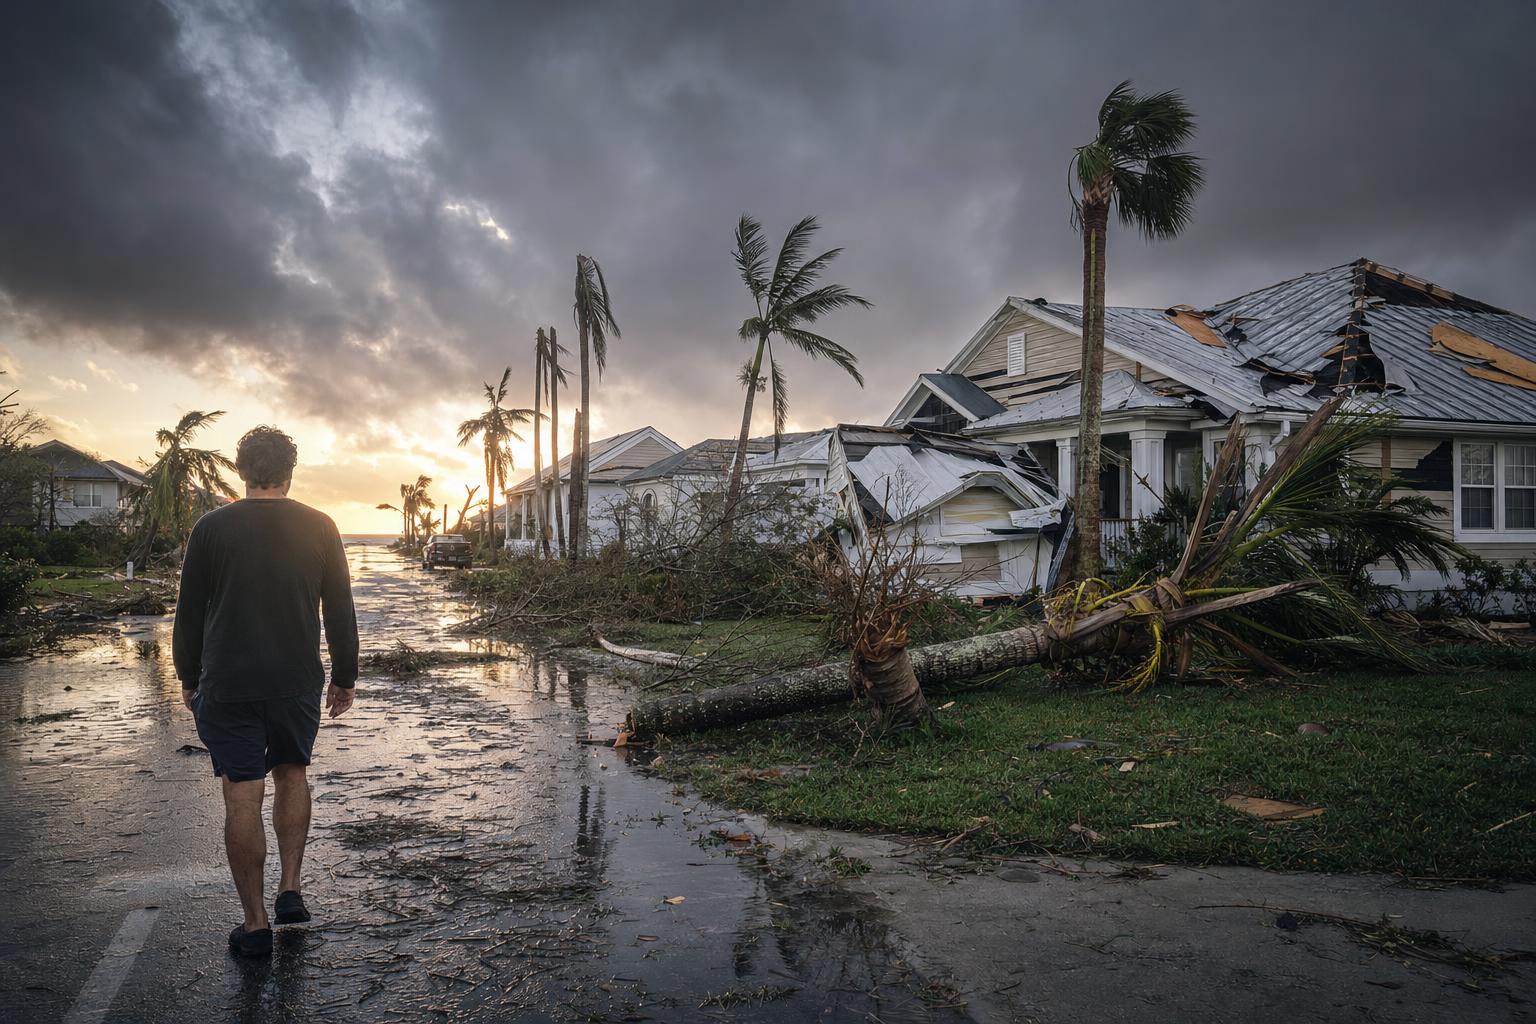
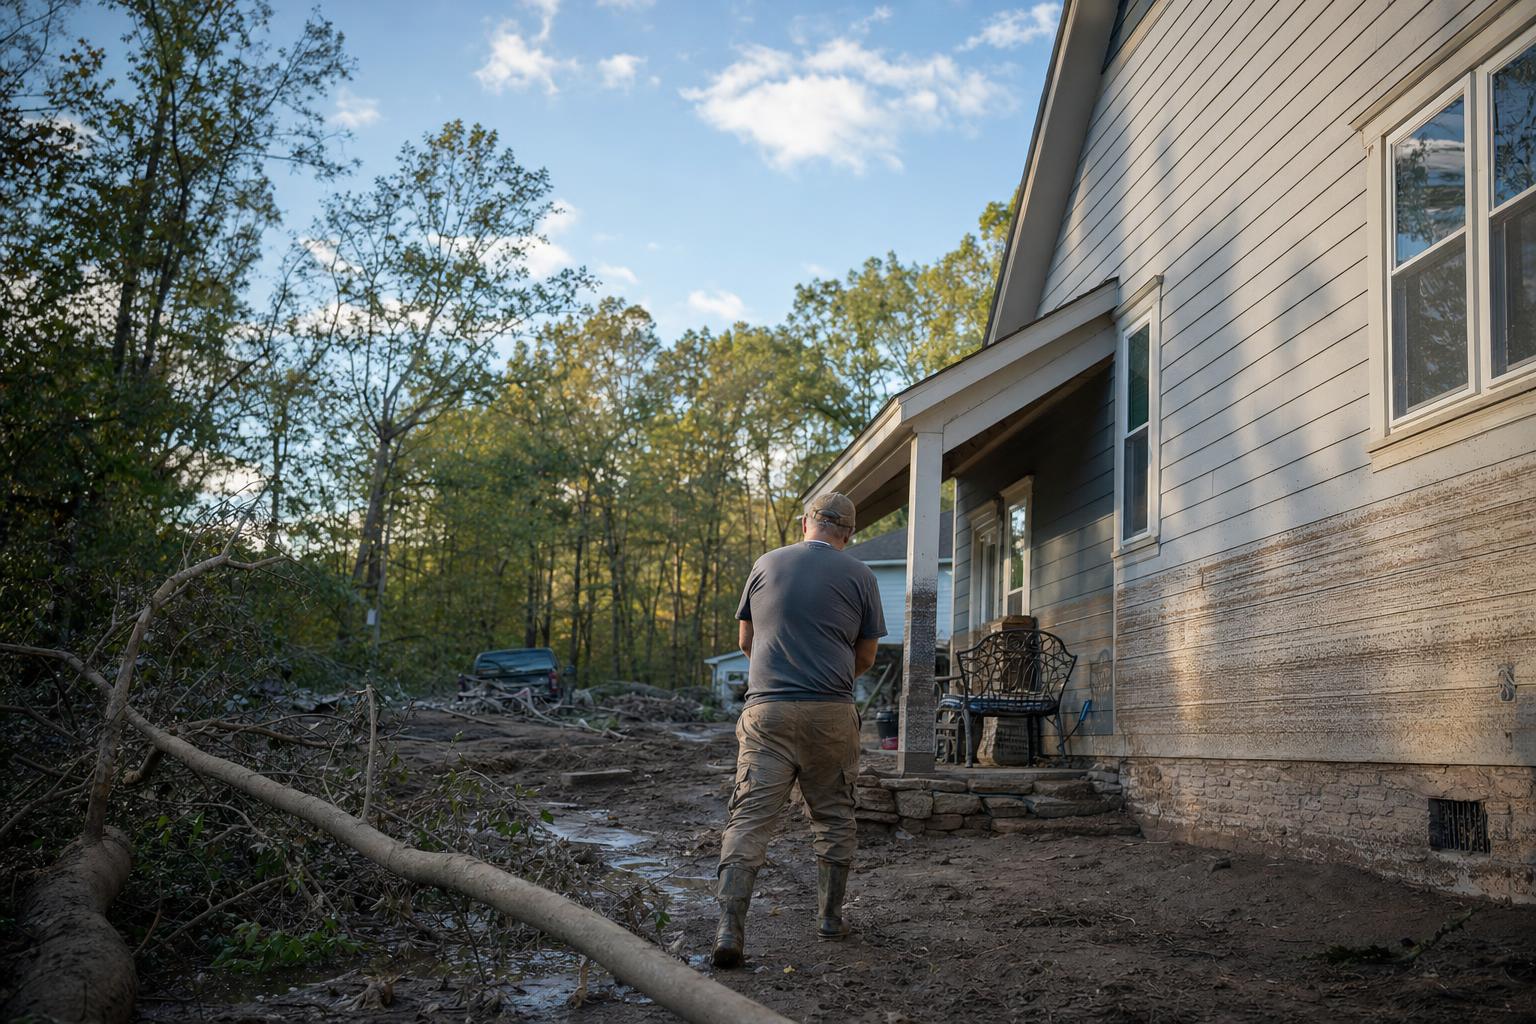
Real past recoveries. Results vary by claim; past results do not guarantee future outcomes.
Every type of claim. Maximum recovery.
Residential Claims
Homeowner property damage claims, handled end to end.
Learn more
Commercial Claims
Business interruption and commercial property losses.
Learn more
Supplement Claims
Underpaid or partially denied claim? We reopen it.
Learn more
Appraisal & Mediation
Dispute resolution when you and the insurer disagree.
Learn more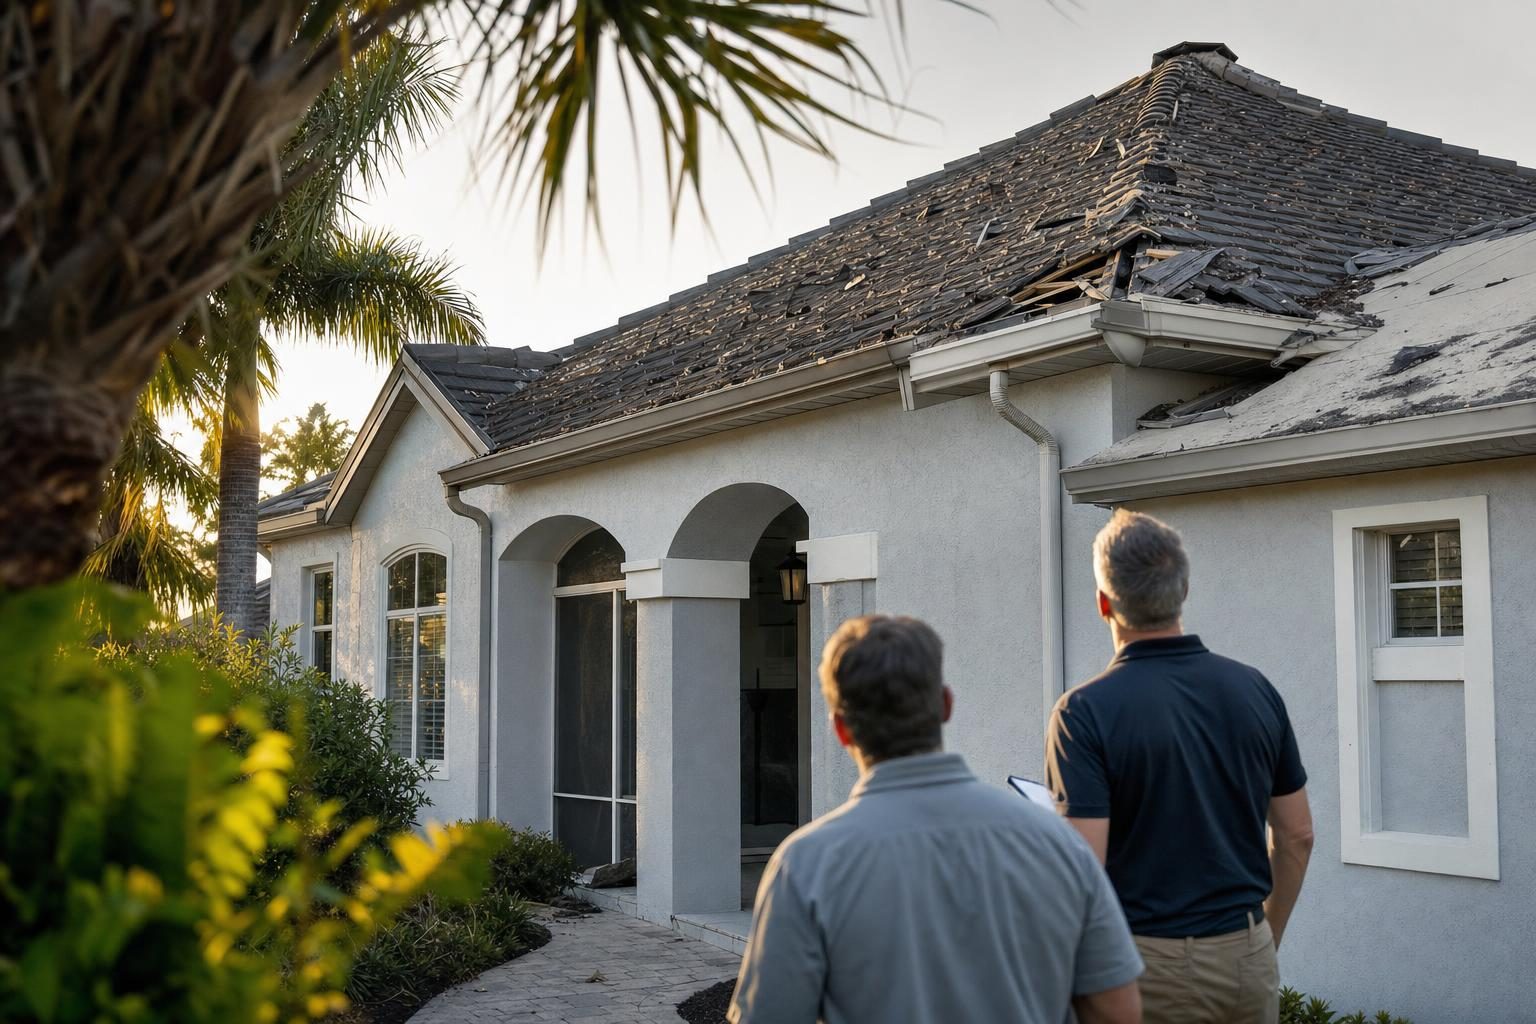
Denied Claims
A denial is rarely the end. We re-inspect, rebuild it, and fight back.
Learn moreHow long do you have to file an insurance claim after a hurricane?
In Florida, hurricane and windstorm claims on policies effective on or after December 16, 2022 must be reported within one year of the date of loss, and supplemental claims within 18 months (Fla. Stat. § 627.70132). In South Carolina, your policy's own notice and proof-of-loss deadlines usually control how fast you must act, and suit on the policy must generally be filed within three years (S.C. Code Ann. § 15-3-530). Either way, hurricane damage claims are won with early reporting and thorough documentation.
How hurricane damage claims work Florida claim deadlines, explained The South Carolina claims guide
Three steps to the settlement you deserve.
 Vanguard Claims · Active case
Free inspection & policy review
We visit your property, document all damage, and review your policy to understand exactly what you're owed, at zero cost to you.
We build your claim
Our team prepares a comprehensive damage report with evidence, accurate repair estimates, and documentation built to withstand insurer pushback.
Negotiate & maximize
We negotiate directly with your insurer on your behalf. We don't stop until you receive the full, fair settlement you deserve.
Real reviews from the policyholders we represent.
4.7 ★ average from 13 verified reviews · Read them on Google
Answers before you call.
Latest claim answers.

Why Insurance Companies Deny Fire Claims, and What to Do About It
Outright fire denials are rare, and they rest on a short list of specific policy grounds. Knowing that list tells you what the carrier is looking for and how to answer it.
Read the article
How Do Insurance Companies Pay Out Claims? The Checks, the Order, and the Holdbacks
A property claim rarely pays in one check. Here is the order the money usually arrives in, who else is named on it, and why the first number is almost never the last.
Read the article
What Is the FEMA 50 Percent Rule? Substantial Damage, Explained for Homeowners
After a flood, a number decided at the permit counter can matter more than your insurance check. If repairs cost half your home's value, the rules change. Here is how the 50 percent rule works.
Read the articleGet the settlement you deserve.
Start with a free claim or policy review. No obligation, no upfront cost.